Newsletter no. 10 – October 2025
Access the magazine version of this Newsletter in pdf format: English or Romanian
Summary
- Procedure to notify ANAF in case of failure to transmit invoice through RO e-Factura system, for situations where payment is made at the time of delivery/performance (Order 2229/2025)
- Extension of certain exceptions related to RO e-Factura system (GEO 52/2025)
- Amendment of the procedure regarding the transmission of information in REGES-ONLINE (Order 2143/2025)
- Update of fiscal registration forms (Order 2420/2025)
- Update of the pre-filled VAT return RO e-TVA (Order 2351/2025) and of the RO e-TVA compliance notification (Order 2394/2025)
- Amendments to legislation on protection and promotion of rights of disabled persons (Law 153/2025)
- New regulations on the prevention of money laundering and the transparency of ultimate beneficial owners (Law 164/2025)
- Extension of rights on home-based work or teleworking for parents with dependent children classified as having a disability (Law 149/2025)
- Update of the value of cultural vouchers (Order 1574/3246/2025) and nursery vouchers (Order 1602/2007/2025)
- Ratification of the conventions to avoid double taxation between Romania and the United Kingdom of Great Britain and Northern Ireland (Law 169/2025) and between Romania and the Principality of Andorra (Law 170/2025)
- Other fiscal news
- Closing exchange rates for October 2025
- Social indicators
Order 2229/2025 to approve Procedure on the notification of the competent fiscal authorities in cases where invoices for supply of goods/provision of services for which payment is made at the time of delivery/performance have not been transmitted through RO e-Factura system within the deadline provided by art. 10, para. 7 of GEO 120/2021 on administration, operation and implementation of national RO e-Factura system and electronic invoicing in Romania, as well as complementing Government Ordinance 78/2000 on vehicle approval process, issuance of vehicle identity cards and certification of authenticity of road vehicles with the scope of introduction to the market, making available on the market, registration in Romania, as well as market surveillance of these vehicles, as well as the measures to be taken by authorities (Official Gazette 895/2025)
Summary
The Order approves procedure for notifying the competent fiscal authorities in cases where invoices for supplies of goods or services paid for at the time of delivery/performance are not transmitted through RO e-Factura system within the legal deadline.
The Order also approves template and content of form (800) Notification regarding invoices for the supply of goods/provision of services for which payment is made at the time of delivery/performance, not transmitted through RO e-Factura system within the deadline provided by art. 10, para. 7 of GEO 120/2021.”
Details
The procedure introduced by this Order covers situations where payment is made at the time of delivery/performance, but the issuer of the invoice fails to fulfill the legal obligation to transmit the invoice to the beneficiary through the RO e-Factura system.
Who can notify ANAF?
- Beneficiaries that have made payment upon delivery/performance and have not received the invoice through the RO e-Factura system within the legal deadline.
Form used
- Form (800) – “Notification on invoices not transmitted through RO e-Factura.”
- The following information should be completed: the date of delivery of goods/provision of services/payment date, as well as the total value of the goods delivered/services rendered.
- The notification should be accompanied by the document proving the date of delivery/performance and the payment document.
- The form is submitted electronically via the Virtual Private Space (SPV).
Notification procedure
- The Beneficiary submits form 800 starting from the day immediately following the expiry of the legal deadline.
- The form is submitted electronically, accompanied by:
- proof of delivery/performance,
- proof of payment.
According to article 10, para. 7 of GEO 120/2021 – “The deadline to transmit invoices in the national system RO e-Factura is 5 calendar days from the date of issuance of the invoice, but no later than 5 calendar days from the deadline provided for issuing the invoice according to art. 319 para. 16 of the Fiscal Code.”
Obligations of the issuer (supplier)
- Receives a message in the Virtual Private Space (SPV).
- Should transmit the invoice(s) subject to notification through RO e-Factura no later than the day following the receipt of the SPV message.
- Should complete the upload index in RO e-Factura using the dedicated functionality available within the system.
Consequences for the issuer
- The issuer is recorded in a special electronic register.
- The issuer is subject to a fiscal risk analysis.
- Additional legal measures may be applied depending on the assessed level of risk.
Details regarding this procedure were presented during our recent Tax Group event on the 17th of October, and subscribers may view the recording of the presentation here:
Emergency Ordinance 52/2025 to amend and complement certain normative acts, to establish measures on the implementation of national programmes in the field of public works, as well as to establish certain budgetary measures (Official Gazette 907/2025)
Summary
The Ordinance extends by the 1st of June 2026, the exemption period from RO e-Factura obligations for individual who are farmers applying the special scheme for farmers and for foreign cultural institutes/centres operating in Romania according to intergovernmental agreements.
Details
The Ordinance extends the exemption from RO e-Factura obligations by the 1st of June 2026 for the following categories:
- Individual who are farmers applying the special scheme for farmers.
- Foreign cultural institutes/centres operating in Romania based on intergovernmental agreements.
- Economic operators – taxable entities established in Romania that supply goods or provide services to foreign cultural institutes/centres operating in Romania (except in cases where the beneficiaries have opted to use the RO e-Factura system).
Farmers starting their activity subsequent to the 30th of May 2026:
- Are required to request registration in the mandatory RO e-Factura Register prior to starting their activity.
- Registration is made within 3 working days from the date of the request.
Order 2143/2025 to amend Annex to the Order of the Minister of Labour, Family, Youth and Social Solidarity 1107/2025 to approve Access Procedure to prepare, transmit and query data in/from the General Staff Register – REGES-ONLINE (Official Gazette 935/2025)
Summary
Order 2143/2025 amends Annex to Order 1107/2025, which establishes the procedure to access, fill, submit and submit query data in/from the General Staff Register (REGES-ONLINE).
The purpose of the amendment is to set clear deadlines for employers to migrate from the previous system (Revisal) to the new REGES-ONLINE platform.
Details
Main amendments
Deadline to request access to REGES-ONLINE
- Employers should request access to the new Register by the 31st of December 2025.
Subsequent to this date, access will be available only through REGES-ONLINE, not through the previous systems.
Obligation to complete and submit data
- By the same date (31.12.2025), employers should complete and submit to REGES-ONLINE all information regarding the individual employment contracts active at the time of access, especially those elements not yet included in the former Revisal system regulated by GD 905/2017.
Transition period between Revisal and REGES-ONLINE
- Employers that have submitted data prior to the entry into force of GD 295/2025 (which introduced REGES-ONLINE) may temporarily continue to submit files from Revisal application:
- either online,
- or at the counter/office of the territorial labour inspectorate but only by their registration in REGES-ONLINE, and no later than the 31st of December 2025.
Repeal of previous procedures (Order 1918/2011)
- Starting the 31st of December 2025, points 4–20 of the Annex to Order 1918/2011 are repealed. These provisions previously regulated:
- the procedure to obtain Revisal password,
- the submission of the register in electronic format. In practice, starting the 1st of January 2026, the Revisal system will be permanently shut down and fully replaced by REGES-ONLINE.

Order 2420/2025 to amend ANAF Presidential Order 1699/2021 to approve tax registration forms of taxpayers and types of fiscal obligations that form the fiscal vector, and ANAF Presidential Order 631/2016 to approve template and content of certain forms for VAT registration/cancellation of VAT registration (Official Gazette 995/2025)
Summary
The Order updates the forms used for tax registration, modification, and deregistration to align with the new VAT exemption threshold of RON 395,000 (effective as of the 1st of September 2025, according to art. 310 para. 1 of the Fiscal Code, as amended by GEO 22/2025).
Details
Updated forms
The update applies to a broad range of ANAF forms used by legal entities, individuals, and non-residents: 010, 013, 015, 016, 020, 030, 040, 070, 700, and 093.
New provisions for taxpayers with headquarters in Romania (forms 010, 016, 020, 040, 070, 700)
1. Updated terminology
- The phrase “intends to reach or exceed” is replaced with “intends to exceed.”
- The phrase “by reaching or exceeding” is replaced with “by exceeding.”
This clarification specifies the exact moment when the exemption threshold is considered surpassed
2. Removal of redundant rows
- Rows 1.4 and 1.8 are eliminated — these previously referred to VAT registration for operations deemed to take place abroad (as per art. 297 para. 4 letters b) and d) of the Fiscal Code).
3. Introduction of a new field: “Date of exceeding the threshold”
- A new row is added to declare the exact date when the threshold of RON 395,000 was exceeded — this date determines when VAT registration becomes effective.
4. Retroactive correction of the VAT registration date
- A new option allows a taxpayer that is already registered and finds that the threshold was exceeded earlier to request a correction of the registration date, so that it coincides with the actual date the threshold was exceeded (as per art. 310 para (6²) of the Fiscal Code).
5. Electronic VAT registration certificate
- Taxpayers registered in the Virtual Private Space (SPV) will receive their VAT registration certificate exclusively in electronic format.
New provisions for taxpayers established outside Romania (forms 013, 015, 030, 093)
1. New row for registration after losing exemption status (art. 310² of the Fiscal Code)
- A new option is added for declaring VAT registration after the cessation of the small business exemption regime.
2. Option to cancel VAT registration
- Taxpayers may now select a new checkbox to renounce VAT registration and apply the exemption regime provided by art. 310² of the Fiscal Code.
3. Clarification for intra-Community acquisitions
- Additional rows are introduced for taxable entities not established in Romania that apply the exemption regime and opt to register for VAT purposes for intra-Community acquisitions, as per art. 317 of the Fiscal Code
Fiscal context
The Order incorporates into forms the amendments introduced by GO 22/2025, which:
- increased the VAT exemption threshold from RON 300,000 to RON 395,000, applicable from the 1st of September 2025;
- implemented EU Directive 2020/285 regarding the special scheme for small enterprises;
- established new rules for VAT registration, deregistration, and re-registration.
Conclusions
ANAF Order 2420/2025:
- updates all tax and VAT registration forms to reflect the new RON 395,000 threshold;
- simplifies and digitalizes the communication process by introducing SPV as the sole electronic channel for transmitting certificates;
- clarifies the procedures for registration, deregistration, and correction of VAT registration dates, for both Romanian entities and non-resident taxpayers.
Order 2351/2025 to amend Annex to ANAF Presidential Order 3775/2024 to approve template and content of the form “Pre-filled RO e-TVA Return” (Official Gazette 942/2025)
Summary
The Order updates the pre-filled VAT return (P300) as a result of the changes to VAT rates effective from the 1st of August 2025.
Details
As a reminder, the pre-filled VAT return is sent by ANAF through SPV by the 5th day of the month following the due date for submitting the standard VAT return (D300).
The e-TVA compliance notifications are also sent online, by the 5th day of the month following the legal deadline to submit the VAT return, if ANAF identifies significant differences between D300 and P300.
The taxpayer is required, within 20 days from receiving the notification, to submit the results of their verification regarding the differences communicated by ANAF.
However, this obligation is suspended by the 31st of December 2025, meaning that the response is optional by that date.
Order 2394/2025 to amend Annex No. 1 to ANAF Presidential Order 6234/2024 to approve template and content of form “RO e-TVA Compliance Notification,” as well as the procedure to transmit the notification (Official Gazette 977/2025)
The Order updates the RO e-TVA Compliance Notification as a result of the changes to VAT rates effective from the 1st of August 2025.
Law 153/2025 to amend Law 448/2006 on protection and promotion of the rights of disabled persons (Official Gazette 961/2025)
Summary
The Law amends Law 448/2006 on protection and promotion of the rights of disabled persons.
Details
According to the new provisions, sales and/or intermediary activities carried out by protected units established within organizations of persons with disabilities will refer exclusively to products and/or services produced partially or entirely through the own activity of employed persons with disabilities and offered by another protected unit authorized in accordance with the law.
This amendment aims to ensure direct involvement of disabled persons in economic activities, thereby strengthening the social mission of protected units.
Compliance with these provisions will be monitored by the fiscal authorities within ANAF.
Law 164/2025 to approve GEO 123/2022 to amend Law 129/2019 on prevention and combat of money laundering and terrorist financing, as well as to amend and complement certain normative acts (Official Gazette 978/2025)
Summary
The Law approves GEO 123/2022 and introduces new obligations on prevention of money laundering and transparency on ultimate beneficial owner, particularly for trusts and national research and development institutes.
Details
The purpose of this new law is to extend the obligation to declare beneficial owners to new types of legal structures (trusts and similar legal constructions), to strengthen the competences of ANAF and to enhance transparency.
Introduction of Article 57¹ in Law 129/2019 – Declaration on beneficial owner of a trust
A new article, art. 57¹, is created, introducing a distinct procedure for the transparency of trusts and similar legal structures.
Main obligations:
- Trustees (or persons holding an equivalent role in a similar legal structure) should declare:
- accurate and complete information regarding the beneficial owner;
- the declaration is submitted to ANAF upon registration of the trust contract, for inclusion in the Register of beneficial owners of trusts (according to art. 19 para. (5) letter c) of Law 129/2019).
Deadlines and sanctions:
- Failure to declare the information results in non-registration of the trust contract by ANAF.
- Any subsequent change on the declared information should be declared within 30 days from its occurrence.
- Failure to declare or update the information constitutes a misdemeanour/ contravention, punishable by a fine ranging from RON 5,000 to 10,000.
- If the data are not updated within 30 days from issuance of the official report, the trust or similar legal construction will be ex officio eliminated from ANAF’s register.
- The procedure for elimination will be established by an ANAF Presidential Order.
- Determination and enforcement of sanctions will be carried out by the fiscal authorities within ANAF and its subordinate units.
Compliance period for existing structures (Article II)
- Existing trustees (or their equivalents in similar structures) who have not declared or updated beneficial ownership data should:
- submit the declaration within 90 days from the date the law enters into force;
- otherwise, they risk a fine of RON 5,000–10,000 and subsequent ex officio elimination from the register.
Introduction of the obligation for national research and development institutes
- These entities are now explicitly required to submit the beneficial ownership declaration:
- upon registration and whenever any change occurs;
- institutes already registered should submit the declaration within 90 days from the entry into force of the law.
This amendment extends the scope of transparency obligations to include public research and development institutions, which had previously been practically exempt.
Competent authorities
- The National Agency for Fiscal Administration (ANAF) becomes the main administrative authority responsible for:
- managing the register of trustees and beneficial owners of trusts;
- verifying compliance and applying sanctions;
- eliminating non-compliant structures from the register.
Conclusions
Law 164/2025:
- transforms ANAF into the control authority and register administrator for trusts and similar legal constructions;
- introduces clear sanctions, including ex officio elimination for non-compliance;
- extends the obligation to declare beneficial ownership to national research and development institutes;
- strengthens Romania’s alignment with EU standards on beneficial ownership transparency (Directive (EU) 2015/849 and its amendments).
Law 149/2025 to complement art. 118^1 of Law 53/2003 – Labour Code (Official Gazette 936/2025)
Summary
The Law complements art. 118¹ of the Labour Code by extending the rights related to remote work (telework) or work from home for parents who have dependent children with disabilities.
Details
Law 149/2025 has a social and family protection purpose, aiming to:
- support parents who take care of children with disabilities;
- facilitate a better balance between professional and family life;
- recognize special family situations, such as those with twins or triplets.
Main amendments:
Right to telework for parents of children with disabilities
- Employees who have dependent children with disabilities, up to the age of 18, are entitled to 8 days per month of work from home or telework.
- Exception: this right does not apply if the nature or specifics of the activity do not allow work under such conditions.
- The right is exercised according to provisions of Law 81/2018 on regulation of teleworking activities.
Additional entitlement for multiple children with disabilities
- If the employee has two or more children with disabilities, an additional 2 days of telework per month is granted for each additional child.
Extension of the right to parents of twins, triplets, or multiple births
- The same right also applies to parents of twins, triplets, or multiple children (up to 18 years old), even if the children are not classified as having a disability.
Required documentation
- The telework request should be accompanied, as applicable, by the certificate of disability classification of the child, issued in accordance with the law.
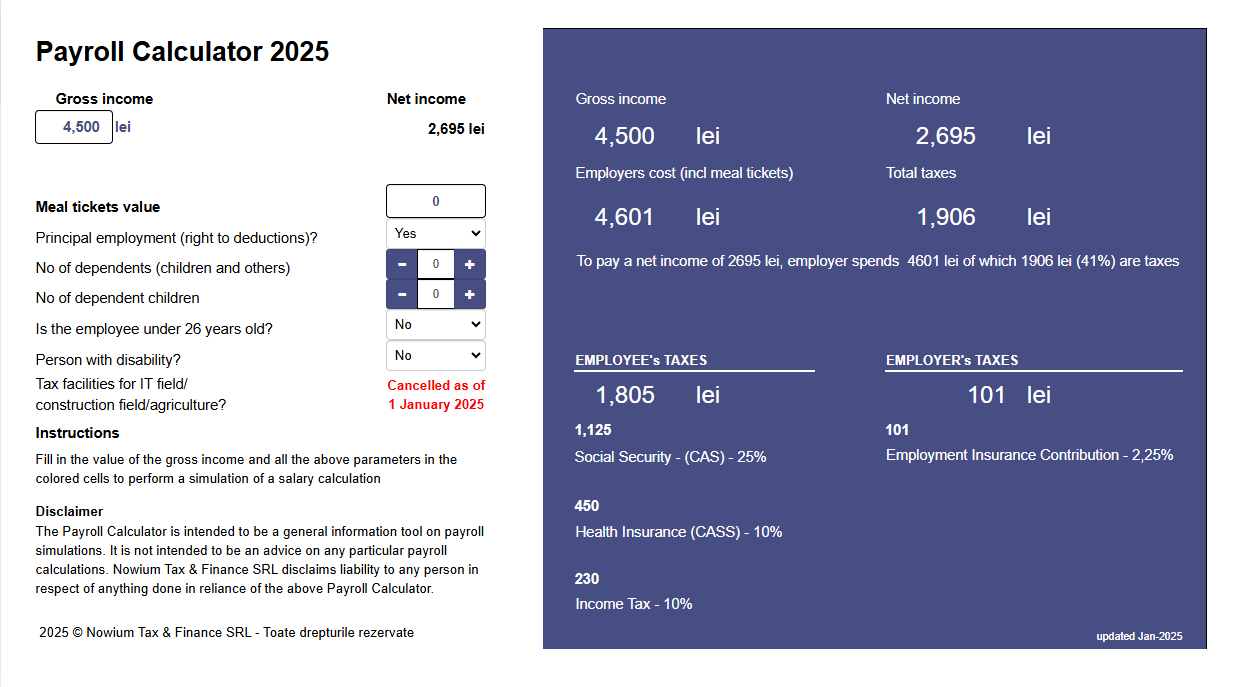
Check out our Payroll Calculator Tool on Nowium’s website
An useful free tool allowing various salary calculation scenarios, updated with the latest legislative changes. https://nowium.com/en/payroll-calculator/
Order 1574/3246/2025 to set indexed value granted as cultural vouchers related to second half of 2025 (Official Gazette 900/2025)
The Order updates the value of amounts granted monthly or occasionally as cultural vouchers:
- Maximum 240 RON per month for monthly vouchers;
- Maximum 470 RON per event for occasional vouchers.
The new values apply for the period October 2025 – March 2026.
Previously, the maximum values were:
- 220 RON/month for monthly vouchers;
- 450 RON/event for occasional vouchers.
Order 1602/2007/2025 to set indexed monthly value granted as nursery vouchers related to second half of 2025 (Official Gazette 899/2025)
The Order updates the value of nursery vouchers.
- Starting October 2025, the monthly amount granted as nursery vouchers is 710 RON (previously 670 RON).
- The new ceiling applies by the 31st of March 2026.
Law 169/2025 to ratify Convention between Romania and the United Kingdom of Great Britain and Northern Ireland for the elimination of double taxation with respect to income and capital gains taxes and the prevention of tax evasion and avoidance, and the Protocol to the Convention, signed in London on the 13th of November 2024 (Official Gazette 996/2025)
The law ratifies the Convention between Romania and the United Kingdom of Great Britain and Northern Ireland for the elimination of double taxation regarding income and capital gains taxes and for preventing tax evasion and avoidance, as well as the Protocol to the Convention, signed in London on the 13th of November 2024.
According to art. 28 of the Convention, it enters into force in Romania on the 1st of January 2026.
Law 170/2025 to ratify Convention between Romania and the Principality of Andorra for the elimination of double taxation with respect to income and capital gains taxes and the prevention of tax evasion and avoidance, and the Protocol to the Convention, signed in New York on the 27th of September 2024 (Official Gazette 996/2025)
The Law ratifies the Convention between Romania and the Principality of Andorra for the elimination of double taxation regarding income and capital gains taxes and for preventing tax evasion and avoidance, as well as the Protocol to the Convention, signed in New York on the 27th of September 2024.
According to art. 28 of the Convention, it enters into force in Romania on the 1st of January 2026.
Order 1334/1600/2025 on complementing the Classification of Occupations in Romania – occupation level (six-character code), approved by the Order of the Minister of Labour, Family and Social Protection and the President of the National Institute of Statistics 1832/856/2011 (Official Gazette 912/2025)
Closing exchange rates for October 2025
The October 2025 closing NBR exchange rates to use for valuation of monetary items (cash on hand, receivables, payables) denominated in foreign currency, as well as receivables and payables denominated in RON but pegged to a foreign currency for collection/disbursement are:
1 EUR = 5,0851 RON; 1 USD = 4,3947 RON; 1 CHF = 5,4787 RON; 1 GBP = 5,7713 RON
The Resources section of our website has an Excel file through which exchange rates are automatically taken from the NBR website and are allocated on each date of validity, according to accounting rules. Thus, the exchange rate communicated by NBR on day N will be displayed on the validity dates N+1…N+2….until the next foreign exchange session.
The closing exchange rate for the month is the exchange rate communicated in the final foreign exchange session of the respective month.
Social Indicators 2025
2025 Contributions - for dependent activities | Employer and beneficiary (for activities considered dependent) | Employee and dependent worker |
Social security contribution (pension) | - Nothing due for normal working conditions | 25% |
Contribution to health insurance fund (calculated on gross income) | Not due | 10% |
Income Tax | 10% | |
Work insurance contribution | 2,25% | |
Disability Fund (for employers with more than 50 employees) | 4 x minimum wage for every 100 employees | |
The amount of a taxable meal ticket in the sense of income tax | max. RON 40.04 | |
Minimum wage (gross) | -> RON 4.050 (starting with January 2025 related income) -> RON 4.582 for employees from construction sector -> RON 4.050 for agriculture and food industry sectors (starting with January 2025 related income) | |
Per Diem (in the country) | 23 lei 57.5 lei | |
The tax facilities granted to employees working in the IT sector, construction, agriculture and the food industry have been eliminated starting with the income related to January 2025. | ||
