Newsletter no. 9 – September 2025
Access the magazine version of this Newsletter in pdf format: English or Romanian
Summary
- REGES-ONLINE transition deadline extended (GEO 46/2025)
- Amendments on VAT threshold, extension of VAT exemption scheme at EU level, postponement of e-VAT sanctions, and other amendments in VAT area (GO 22/2025)
- Amendments on global minimum level of taxation of multinational enterprise groups and large-scale domestic groups (“Pillar 2”) (GO 21/2025)
- Update of VAT return form 300 (Order 2131/2025)
- Update of form 394 (Order 2194/2025)
- Procedure to reimburse VAT related to purchase of goods or services carried out by NGOs and companies entirely owned by NGOs (Order 1480/2025)
- Update of Procedure to organise the Register of houses purchased applying reduced VAT rate (Order 2149/2025)
- Update of Procedure to submit tax returns by electronic means of remote transmission (Order 2213/2025)
- Update of provisions on the application of the reduced VAT rate for the supply of fertilizers/pesticides/seeds, as well as for the provision of services of the type normally used in agricultural production (Order 313/1515/2025)
- Rules on authorization and use of the special mechanism to declare and pay VAT related to import (Order 2618/2025)
- Other legislative news
- Closing exchange rates for September 2025
- Social indicators
Emergency Ordinance 46/2025 to amend and complement GEO 17/2005 to set organizational measures for central public administration, as well as to amend certain normative acts (Official Gazette 863/2025)
The Ordinance extends the deadline for the transition to the new REGES-ONLINE system from the 30th of September 2025 to the 31st of December 2025. More details about REGES-ONLINE:
Ordinance 22/2025 to amend and complement Law 227/2015 on the Fiscal Code (Official Gazette 806/2025)
Summary
The Ordinance introduces amendments and complements to the Fiscal Code on VAT application regime starting from the 1st of September 2025.
Details
Increase of the VAT exemption threshold to RON 395,000
The threshold to apply the special VAT exemption scheme has been increased from RON 300,000 to RON 395,000. In this context, taxpayers exceeding this new turnover limit should request VAT registration no later than on the date of exceeding the threshold. They should apply the standard taxation regime starting with the transaction through which the threshold is exceeded. Thus, the 10-day period for registration formalities is eliminated – the obligation arises immediately.
Invoices issued without VAT which led to the exceeding of the threshold should be corrected, so that the beneficiaries may exercise their right of deduction in accordance with the legal provisions.
What does the turnover include?
The turnover relevant for the exemption threshold refers only to operations with the place of supply in Romania, carried out during a calendar year, and consists of:
- total value (without VAT) of supplies of goods and provisions of services that are taxable or exempt with the right of deduction;
- exempt operations without the right of deduction (if they are not ancillary to the main activity), according to art. 292 para. (2) letters a), b), e) and f) of the Fiscal Code.
The following are not included in the turnover::
- supplies of tangible fixed assets;
- assignment or transfer of intangible assets.
What happens if registration is omitted or delayed?
If the taxpayer does not request registration on time:
- They apply for retroactive VAT registration as of the date of exceeding the threshold, or, if already registered, requests the change of the registration date.
- They calculate VAT to be paid, representing the difference between collected VAT and deductible VAT, if the collected VAT is higher.
- They determine the negative VAT amount, if deductible VAT is higher than collected VAT.
Submission of the VAT return
The amounts resulting from these calculations are registered in:
- the first VAT return submitted after registration or modification of the registration date;
- or in a subsequent return, depending on the case.
Transitional rules on new VAT exemption threshold (RON 395,000)
1. Exceeding the threshold of RON 300,000 in August 2025
Taxpayers which only exceeded the old threshold (RON 300,000) in August 2025 are not required to register immediately under the scope of VAT. They will only apply for registration if they exceed the new threshold of RON 395,000.
2. Exceeding the threshold of RON 395,000 in August 2025
Those which also exceeded the new threshold in August 2025 should apply for VAT registration no later than the 10th of September 2025 (according to previous provisions). The standard taxation regime applies starting the 10th of September, the date from which the registration is considered valid.
3. Taxpayers established prior to 2025
If they registered under the scope of VAT by 1st of September 2025 due to exceeding the RON 300,000 threshold, they may request deregistration starting the 1st of September, provided that:
- they did not exceed the RON 300,000 threshold in 2024;;
- they did not exceed the RON 395,000 threshold by the date of the request.
4. Taxpayers established in 2025
If they registered under the scope of VAT by the 1st of September 2025 due to exceeding the RON 300,000 threshold, they may request deregistration starting the 1st of September, provided that:
- they did not exceed the RON 395,000 threshold by the date of the request.
Introduction of new rules allowing the extension of the VAT exemption scheme
Taxable entities with their place of business in Romania may opt to apply the VAT exemption scheme in other Member States. To this end, regardless of the number of Member States involved, a notification should be submitted to ANAF to obtain a special code, and the following conditions should be met:
- the annual turnover at EU level of the taxable entity does not exceed EUR 100,000 during the year when the exemption is requested and the previous calendar year;
- the value of the supplies of goods and services performed in the Member State where the taxable entity intends to apply the exemption does not exceed the exemption threshold applicable to taxable entities established in that Member State.
Reference is also made to taxable entities whose place of business is in other Member States and which opt to apply the VAT exemption scheme in Romania. In this case, the notification is submitted to the authorities of the Member State of establishment, and the following conditions should be met:
- the annual turnover at EU level does not exceed EUR 100,000 during the year when the exemption is requested and the previous calendar year;
- the value of the supplies of goods and services performed in Romania does not exceed the VAT exemption threshold of RON 395,000 during the year when the exemption is requested and the previous calendar year.
Postponement of sanctions related to e-VAT system
Sanctions related to e-VAT system have been suspended by the 31st of December 2025. Thus, sanctions will apply again as of the 1st of January 2026
Amendments on determination of the place of supply of certain services
For B2C transactions carried out between taxable entities (suppliers) and non-taxable entities/individuals (final consumers), the place of supply of services will depend on the way these services are provided, as follows:
- for services related to cultural, artistic, sporting, scientific, educational, entertainment activities, fairs, exhibitions and other similar activities carried out in a physical venue – the place of taxation will be the Member State where the event takes place;
- if the same services are provided virtually/digitally – the place of taxation will be the Member State where the beneficiary is established or has its domicile.
For B2B transactions carried out exclusively between taxable entities, the principle is maintained that the place of taxation is the Member State where the event actually takes place.
Simplified invoicing
The Ordinance extends the right to issue simplified invoices to taxpayers applying the VAT exemption scheme (art. 310 and 310¹ Fiscal Code), regardless of the value of the invoice.
This applies both to:
- taxable entities established in Romania;
- taxable entities established in other EU Member States.

Ordinance 21/2025 to amend and complement Law 431/2023 on ensuring a global minimum level of taxation of multinational enterprise groups and large-scale domestic groups (Official Gazette 805/2025)
Summary
The Ordinance introduces amendments to regulations on ensuring a global minimum level of taxation of multinational enterprise groups and large-scale domestic groups (also known as “Pillar 2”).
Details
The main amendments are as follows:
- Definition of the concept “transferable tradable tax credit.” This means a tax credit that may be used by the credit holder to reduce their liability to pay a tax covered according to legislation of the jurisdiction that has regulated this tax credit, namely what constitutes the attributes of transferability and tradability of this credit. These standards are defined both for the initial holder of the credit and for its purchaser. For the analysis of compliance with the tradability standard, the transaction price is also relevant, with its elements being set out in the OECD Model Rules Commentary;
- National top-up tax rules. Where not all constituent entities located in Romania meet the condition of applying the same accounting regulations, or where the fiscal year of the constituent entities in Romania differs from the fiscal year used as a reference in the consolidated financial statements of the multinational group, the term “national top-up tax” is replaced with the term “national excess profit”;
- Complement of the national top-up tax calculation formula. The formula is complemented by adding the additional national top-up tax, which is the tax determined in accordance with the tax rules established for the additional top-up tax for the relevant financial year;
- Complementing the tax rules for equity reduction operations. These are operations by which a constituent entity reduces its equity as a result of distributions made or due in relation to an instrument issued by that constituent entity in accordance with prudential regulatory requirements, classified as “Tier 1 own funds items” for insurance investment entities.
Order 2131/2025 to approve template and content of form (300) “VAT Return” (Official Gazette 826/2025)
Summary
The Order updates template and content of form (300) “VAT Return,” following the VAT rate changes applicable as of the 1st of August 2025.
Details
Among the main amendments are:
- two distinct sections have been introduced, indicating either the NACE code applicable for the year 2024 or the one applicable for the year 2025;
- new rows have been introduced for highlighting transactions subject to new VAT rates.
The new form 300 shall be used starting with tax obligations related to August 2025, respectively 3rd quarter of 2025.
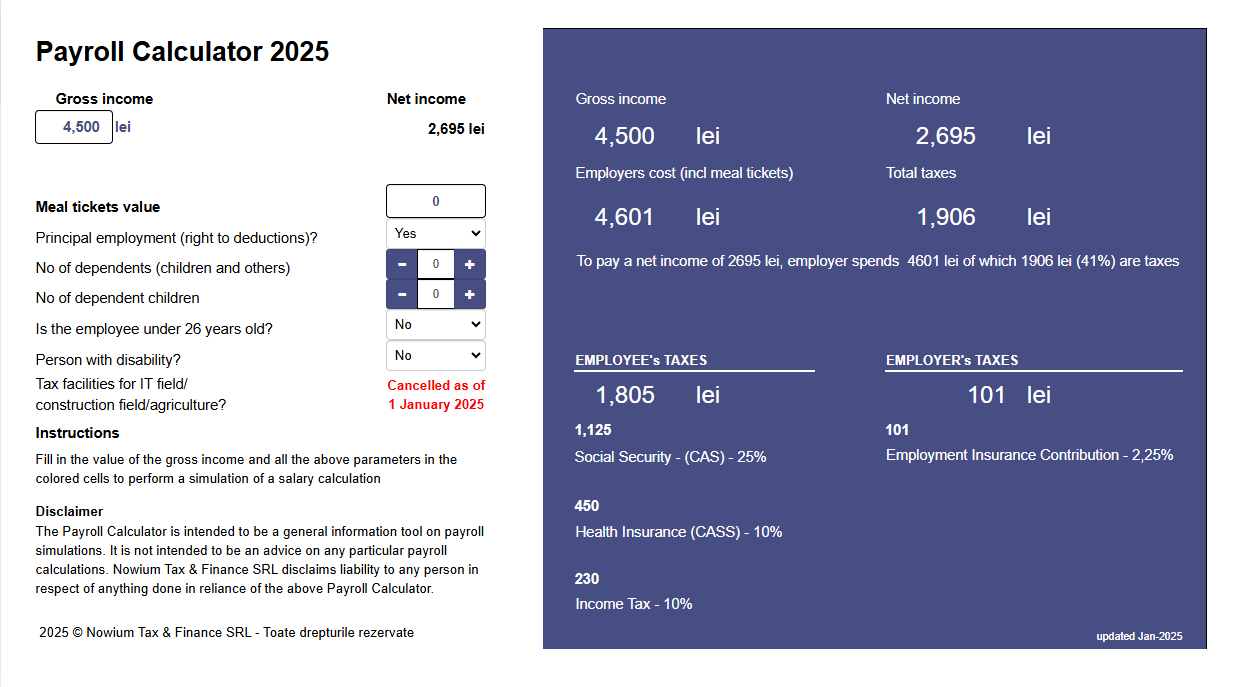
Check out our Payroll Calculator Tool on Nowium’s website
An useful free tool allowing various salary calculation scenarios, updated with the latest legislative changes. https://nowium.com/en/payroll-calculator/
Order 2194/2025 to amend ANAF Presidential Order 3769/2015 on declaring deliveries/services and purchases made in the national territory by entities registered for VAT purposes and approving template and content of informative declaration on deliveries/services and purchases made on national territory by entities registered for VAT purposes (Official Gazette 852/2025)
The Order updates template, content, and instructions to fill-in the form 394 “Informative statement on deliveries and purchases made on national territory by entities registered for VAT purposes.”
The update of form 394 was necessary given the VAT rate changes applicable as of the 1st of August 2025.
Order 1480/2025 to approve Procedure to reimburse VAT for operations provided under art. 294 para. (5) letters a)–b¹) of Law 227/2015 on the Fiscal Code, in force by the 1st of August 2025, where the chargeable event occurred prior to the 1st of August 2025 (Official Gazette 832/2025)
Summary
The Order approves the Procedure to reimburse VAT related to acquisition of goods or services carried out by NGOs and companies entirely owned by NGOs, for which the VAT exemption applies under art. 294 para. (5) letters a)–b¹) of the Fiscal Code, in force by the 1st of August 2025, where the chargeable event occurred prior to the 1st of August 2025.
Details
Categories of acquisitions eligible for VAT reimbursement
1. Building, rehabilitation and modernization services of hospital units, provided to:
- NGOs registered in ANAF’s public register;
- companies entirely owned by NGOs.
Condition: the services should be made available free of charge to public hospital units or intended for hospital units owned and operated by the respective NGOs/companies.
For companies, additional conditions apply:
- hospital units and shares cannot be transferred to private entities for a period of 20 years;
- profit should be reinvested for development of the units or for free medical services provided to disadvantaged persons.
2. Supplies of medical equipment and materials, including:
- devices, instruments, protective equipment, sanitary consumables;
- goods for persons with disabilities (including adaptation, repair, rental, leasing).
Recipients should be:
- NGOs or companies entirely owned by them;
- the goods should be donated or made available free of charge to public or own hospital units.
The same conditions of non-transferability and reinvestment apply as in the case of services.
Order 2149/2025 to amend and complement Annex to ANAF Presidential Order 2080/2023 to approve Procedure to organize Register for purchase of houses where reduced VAT rate is applied (Official Gazette 839/2025)
Summary
The Order updates Procedure to organize Register for purchase of houses where reduced VAT rate is applied, given the new fiscal amendments brought to the Fiscal Code by Law 141/2025, applicable as of the 1st of August 2025.
Details
Under this new legislative framework, a transitional regime was introduced, allowing, by the 31st of July 2026, the application of the reduced 9% VAT rate for the purchase of a single house, provided that the preliminary sale-purchase agreement was concluded and the advance payment was made prior to the 1st of August 2025. Eligible houses should have a usable area of no more than 120 sqm and a value of maximum RON 600,000, without VAT
To reflect these amendments, the obligations of public notaries regarding the completion of the Register have been updated, as follows:
- by the 31st of July 2026, public notaries shall enter in the Register the information from legal acts between living persons concerning the transfer of ownership rights over houses acquired with the 9% reduced VAT rate, by individuals, individually or jointly;
- the Register shall be completed on the date of authentication of the legal acts between living persons;
- in order to check whether an individual has already benefited from the reduced VAT rate for another house as of the 1st of January 2023, the notary shall consult the Register of acquisitions, which also includes data from the Register related to the 5% VAT rate;
- if, following the check, it is found that the person is already listed in the Register as the beneficiary of a house with reduced VAT, the authentication of a new legal act or advance payment shall only be carried out if the supply is made with the standard VAT rate;
- information on houses purchased under the transitional regime shall be recorded in the dedicated section of the Register.
Order 2213/2025 to approve Procedure for submission of tax returns by electronic means of remote transmission (Official Gazette 860/2025)
Summary
The Order approves Procedure for submitting certain tax returns by electronic means of remote transmission, namely:
- form 150 “Application to use of a qualified certificate;”
- form 151 “Application to revoke the right to use Online Submission of Tax Returns service.”
Details
The application to use a qualified certificate (form 150) is to be completed and submitted electronically, signed with a qualified electronic signature by the taxpayer or by the authorized person. Where applicable, the application should be accompanied by the power of attorney signed electronically or by a document certifying the representative’s capacity, all included in a file containing the supporting documents corresponding to the data in the application.
If the power of attorney is not submitted in electronic format, the fiscal authority shall notify the applicant by e-mail within 5 days from the registration of the application, informing them that approval will be carried out directly at the fiscal authority’s office.
If the taxpayer is represented by a lawyer, fiscal consultant, or chartered accountant, the power of attorney should comply with the form and content provided by the regulations specific to the respective profession.
If the application is not signed electronically, it may be submitted physically at the fiscal authority’s office, together with the supporting documents. The fiscal authority shall verify the validity of the information and communicate the approval or rejection decision by e-mail.
The revocation of the right to use the service for online submission of tax returns is carried out by completing form 151, which may be submitted electronically or, in the absence of an electronic signature, submitted physically with the fiscal authority. The revocation decision shall be communicated to the taxpayer by e-mail
Order 313/1515/2025 to amend Order of the Minister of Finance and of the Minister of Agriculture and Rural Development 4634/397/2022 to apply the reduced 9% VAT rate for supply of fertilizer and pesticides normally used in agricultural production, seeds and other agricultural products intended for sowing or planting, as well as for provision of services normally performed in agricultural production (Official Gazette 869/2025)
The Order updates the existing provisions regarding the application of the reduced VAT rate for supply of fertilizer and pesticides normally used in agricultural production, seeds and other agricultural products intended for sowing or planting, as well as for provision of services normally performed in agricultural production. Accordingly, all references to the reduced 9% VAT rate are replaced with the new reduced rate of 11%.
Order 2618/2025 to approve Rules on authorization and use of the special mechanism to declare and pay VAT related to import, and template and content of the special VAT return (Official Gazette 814/2025)
Summary
The Order approves Rules on authorization and use of the special mechanism to declare and pay VAT related to import, and template and content of the special VAT return.
Details
Purpose of the mechanism
A special procedure is introduced to declare and pay VAT related to import, applicable to goods with a value not exceeding EUR 150, the dispatch or transport of which is completed in Romania.
Authorization conditions
The applicant should cumulatively meet the following requirements:
- express the intention to use the special mechanism;
- be a postal operator or customs broker;
- be registered under the scope of VAT;
- have no outstanding fiscal or customs debts;
- not be subject to insolvency proceedings;
- provide a guarantee covering the deferred import VAT.
Authorization procedure
- An electronic application is submitted to the customs office.
- If the application is complete, it is accepted; otherwise, the applicant has 30 days to complete it.
- The customs office shall notify the amount of the guarantee and the deadline for its establishment (maximum 30 days).
- The authorization is issued only after the guarantee has been provided.
Subsequent obligations of the authorization holder
- monthly submission of the special VAT return;
- keeping electronic registers;
- notifying the customs office of relevant changes;
- correct VAT collection from recipients;
- the customs office will carry out periodic checks.
Correction of the special VAT return
- Corrections may be made within 3 years from the date of the initial submission;
- All fields should be completed with the correct data;
- A corrective return should be submitted for each altered period.
Other legislative news
Order 143/2025 to approve supervision mechanism for the activity of associations and foundations established according to GO 26/2000 on associations and foundations (Official Gazette 865/2025)
The Order approves supervision mechanism for the activity of associations and foundations established according to GO 26/2000 on associations and foundations, as approved with its amendments and complements by Law 246/2005.
Order 2221/2025 repealing ANAF Presidential Order 1892/2016 to approve Technical Norms to use and file customs declaration and disclosure notes on codes used for customs declarations (Official Gazette 877/2025)
Order 1485/2025 to approve Procedure to request and transmit the fiscal attestation certificate, for the purpose of solving applications for granting the status of authorized declarant within CBAM, by the General Directorate of Fiscal Legislation and Customs and Accounting Regulations – CBAM and Green Taxes Directorate within the Ministry of Finance (Official Gazette 838/2025)
Order 2175/2025 to amend ANAF Presidential Order 1193/2021 to approve Procedure for registration of trust contracts or legal instruments similar to a trust, for the organization and functioning of the Central Register of Trusts and of legal instruments similar to trusts, for approval of Procedure for access to the Central Register of Trusts and Legal Instruments similar to trusts, as well as for approval of template and content of certain forms (Official Gazette 857/2025)
Regulation 3/2025 to amend and complement Regulation of the National Bank of Romania 4/2021 on reporting data and statistical information to the NBR (Official Gazette 853/2025)
Closing exchange rates for September 2025
The September 2025 closing NBR exchange rates to use for valuation of monetary items (cash on hand, receivables, payables) denominated in foreign currency, as well as receivables and payables denominated in RON but pegged to a foreign currency for collection/disbursement are:
1 EUR = 5,0811 RON; 1 USD = 4,3247 RON; 1 CHF = 5,4253 RON; 1 GBP = 5,8159 RON
The Resources section of our website has an Excel file through which exchange rates are automatically taken from the NBR website and are allocated on each date of validity, according to accounting rules. Thus, the exchange rate communicated by NBR on day N will be displayed on the validity dates N+1…N+2….until the next foreign exchange session.
The closing exchange rate for the month is the exchange rate communicated in the final foreign exchange session of the respective month.
Social Indicators 2025
2025 Contributions - for dependent activities | Employer and beneficiary (for activities considered dependent) | Employee and dependent worker |
Social security contribution (pension) | - Nothing due for normal working conditions | 25% |
Contribution to health insurance fund (calculated on gross income) | Not due | 10% |
Income Tax | 10% | |
Work insurance contribution | 2,25% | |
Disability Fund (for employers with more than 50 employees) | 4 x minimum wage for every 100 employees | |
The amount of a taxable meal ticket in the sense of income tax | max. RON 40.04 | |
Minimum wage (gross) | -> RON 4.050 (starting with January 2025 related income) -> RON 4.582 for employees from construction sector -> RON 4.050 for agriculture and food industry sectors (starting with January 2025 related income) | |
Per Diem (in the country) | 23 lei 57.5 lei | |
The tax facilities granted to employees working in the IT sector, construction, agriculture and the food industry have been eliminated starting with the income related to January 2025. | ||
